Revolut’s decision to remove USDT from its platform is more than a routine product update. It illustrates what happens when digital asset distribution moves from an adaptable commercial setting into a licensed regulatory framework.
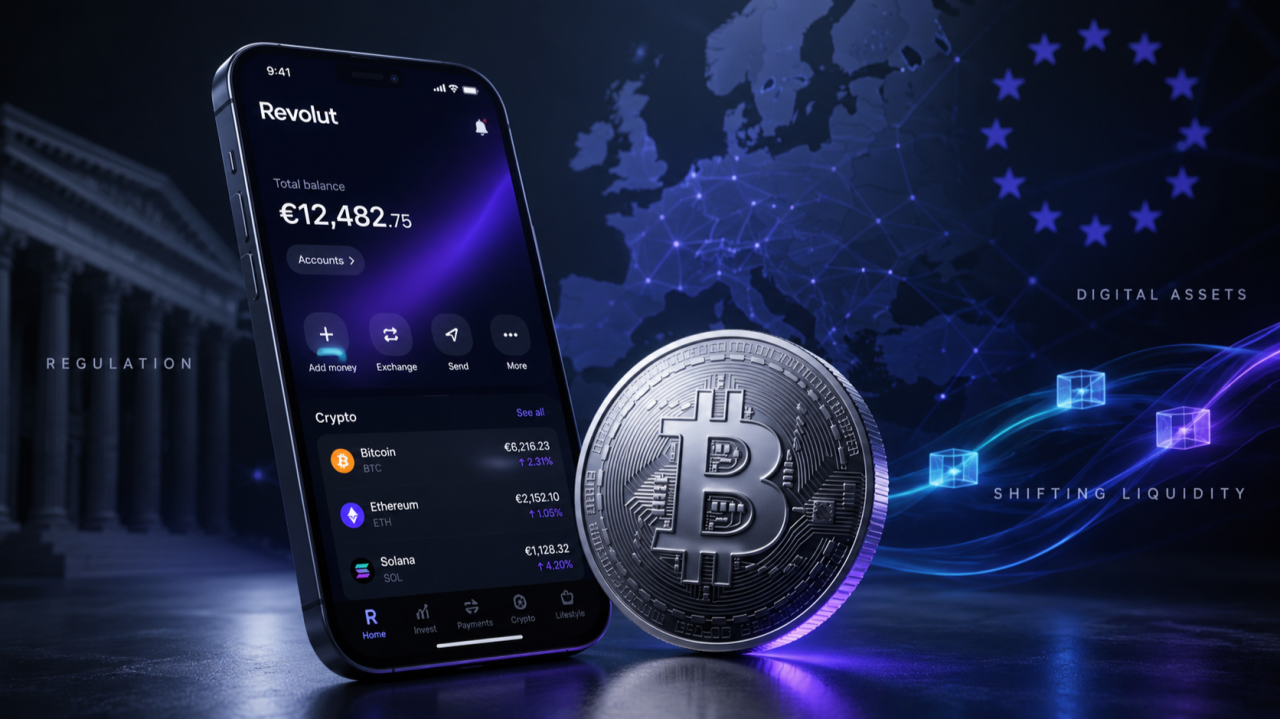
Revolut has notified certain customers that USDT purchases will cease in July, with deposits restricted later that month and full delisting scheduled after 31 August 2026. Remaining holdings may convert to the user’s base currency. For one of the world’s largest fintech platforms, this is a notable change in stablecoin accessibility — and the critical issue is not that USDT lost utility, but that Revolut’s regulatory standing shifted.
The MiCA Perimeter Changed the Product Set
Throughout the MiCA transition, major crypto platforms took varying approaches to USDT in Europe. Coinbase discontinued USDT for European users in December 2024, and others followed. Revolut held on longer while expanding its crypto services, including stablecoin conversion features and a wider range of digital assets.
That flexibility became harder to sustain once Revolut obtained MiCA authorisation through Cyprus and moved its European crypto operations into a fully regulated framework. MiCA-authorised crypto-asset service providers operate within a narrower perimeter: stablecoins distributed in Europe must originate from authorised issuers and meet the applicable reserve, governance and disclosure standards. Tether chose not to bring USDT into the MiCA framework, leaving Revolut with a straightforward compliance problem — a licensed European platform cannot indefinitely treat a non-MiCA stablecoin as if the regulatory perimeter does not apply.
Why Tether Did Not Follow Europe
Tether’s position reflects rational business reasoning. USDT’s financial model depends heavily on holding highly liquid dollar assets, particularly short-dated U.S. Treasury securities, with reserve yields funding Tether’s profitability.
MiCA changes the reserve structure required of major stablecoin issuers, requiring substantial reserves to be held as deposits within European credit institutions. That may improve regulatory oversight, but it shifts the risk and return profile of the reserve portfolio — and would require Tether to accept less flexibility, more bank-counterparty exposure, and potentially weaker economics than its current model. The 2023 USDC depeg is a reminder of why that trade-off matters: it stemmed not from a blockchain failure but from concerns about bank deposits at Silicon Valley Bank. MiCA does not recreate that exact situation, but it does increase the importance of bank deposits within reserve architecture. Tether examined the economics and declined to participate.
Circle Gains the Regulated Channel
The clearest winner is Circle. Although USDC is substantially smaller than USDT globally, it is positioned more favourably for regulated market entry. Within Europe, MiCA creates a clearer pathway for compliant stablecoins through licensed platforms, institutional partners and retail-focused fintech channels. This does not mean USDC replaces USDT internationally — USDT remains deeply embedded in global crypto liquidity, emerging-market dollar access, cross-border payments and offshore trading. Its strongest use case sits in markets that prioritise dollar liquidity over European regulatory endorsement. Europe may reduce USDT’s accessibility through licensed platforms, but that does not eliminate the underlying demand for it.
Liquidity Does Not Disappear
USDT demand will not vanish on 1 September. It will relocate. Some users will move to MiCA-compliant stablecoins; others will shift to self-custody wallets, offshore exchanges or non-European venues; and institutional participants will adapt through jurisdictional routing, alternative settlement systems and regulated wrappers where needed.
“Regulation rarely eliminates financial demand. More often, it changes where that demand can be expressed, how it is intermediated, and which infrastructure captures the flow.” — Michael Moss
MiCA may deliver a cleaner compliance picture for regulated European platforms, but some of the activity it restricts will likely migrate beyond the licensed perimeter rather than disappear.
The Market Infrastructure Lesson
The Revolut-USDT episode is about more than stablecoins — it speaks to the trajectory of digital asset distribution generally. The winning infrastructure will not be the platform with the broadest product selection across every jurisdiction. It will belong to the entities that understand how regulation, custody, issuance, settlement and distribution interact internationally, including:
- Jurisdictional routing: directing flows to the venues and wrappers that match each investor’s regulatory posture.
- Custody selection: matching custodial arrangements to the compliance requirements of the underlying instrument.
- Regulated distribution channels: identifying which licensed rails can actually carry the exposure to end investors.
For platform advisors, asset managers and financial institutions, the question is no longer whether demand for digital dollar liquidity exists — it demonstrably does. The more pressing question is how to structure that exposure: where it originates, which custodial arrangements it uses, and which regulated distribution channels carry it to investors.
AYMONE is built around exactly this infrastructure challenge — transforming financial exposures into investable, custody-compatible and distribution-ready securities across regulated markets. MiCA has not closed the book on Europe’s stablecoin story; it has made the wrapper, the jurisdiction and the settlement rail more consequential than before.